Resources For Aging Well

Have questions about Aging? Here at Seniors Blue Book, we are all things SENIOR. Come explore local options or connect with one of our specialists to help your search.

Since 1983 the Seniors Blue Book has helped Millions of Seniors & Caregivers navigate the confusing world of Senior Housing, Senior Care, Resources and Services. Let us be your guide in helping you find the information you need, when you need it most. For absolutely FREE.

Start Searching
banner image
Age Gracefully

Age Gracefully - and with
Purpose

With the help of Seniors Blue Book, you will soon discover all your living options and know what services are available to you to live your best life. Seniors Blue Book is a complete resource. We strive to list all assisted living, memory care, nursing homes, retirement communities as well as home healthcare and local senior services. Providing local Information you can trust, we are a directory, not a referral service that shares your information without your consent.

The Handbook for successful
Senior Living

Senior Living Community or Living at Home? Home Health Care or Non-Medical Home Care? What Services are available to help me live at home? What is there to do today? The Seniors Blue Book is here to help!

  • Search our national database
  • Visit one of our 28 printed edition markets
  • Chat for free with a Resource Specialist
  • Explore local and national events for education and entertainment
  • View articles and videos to educate
The Handbook

Navigating the Senior Maze can be
an overwhelming process

Let us help you, when you need us most.

Navigating image

Why Trust us?

The Seniors Blue Book is the resource of choice in every market we serve. We are experts at what we do, with a brand nearly 40 years in the industry. Our team is committed to providing the most complete and comprehensive resources available and are constantly working on compiling new information and updates. In addition to providing the upmost accurate information, we offer an extensive Educational Library with thousands of articles, videos, definitions, and commonly asked questions.

Helping Seniors and Caregivers navigate the maze of senior life, while RESPECTING YOUR PRIVACY.

Providing local information you can trust, we are a directory, not a referral service that shares your information without your consent. We list all senior living options: Assisted Living, Memory Care, Nursing Homes and Retirement Communities as well as Home Healthcare, Activities, and Education.

The Seniors Blue Book is a FREE resource to all.

Need a book? We can mail you one. Need personal guidance? Contact us, we will help. It’s what we do!

Our information is Accurate & routinely updated.

We list all licensed communities and agencies with actual prices & offerings, not just estimated guesses. This information is available to you at any time, as we do not require your personal information for access.

call Men
Don’t be shy, Say Hello! Talk to a

Local Resource Specialist, it’s absolutely Free!

Call us at 800-201-9989 or Chat Now!

Resources image

Seniors Blue Book- A Complete Resource Guide

Know your options when it comes to Senior Living and Lifestyle. Seniors Blue Book lists all housing, home health and service options available.

For nearly 40 years, we have helped Millions of Seniors & Caregivers navigate the confusing world of Senior Housing, Senior Care, Resources and Services.

Senior Resources and Tools

...

Ask an Expert

Our Local Publishers are here to help you find the best Housing and Services options available. Contact Us today if you are in need of unbiased, informed guidance.

Ask Now
...

Order A Book

Order your FREE printed edition today! The Seniors Blue Book prints 3 Million copies annually serving 28 markets.

Order Now
...

Local Newsletter Sign-Up

Events, Seminars, Educational Opportunities and so much more. Sign up today for your FREE newsletter to be in the know of what’s going on in your local community.

Sign Up Now

MEDICARE

Looking for Medicare services near you?

Our Medicare Search tool helps you locate dialysis facilities, doctors, home health services, hospice care, hospitals, rehab facilities, long-term care hospitals, nursing homes, and medical equipment providers.

Discover all your local Medicare choices effortlessly and make informed decisions.

Order A Printed Edition

Pick Up A Local Book

Understand Your Senior Care Options

Our Newest Editions

Trusted Options

HealthLight Light Therapy Devices

Pain Management Device

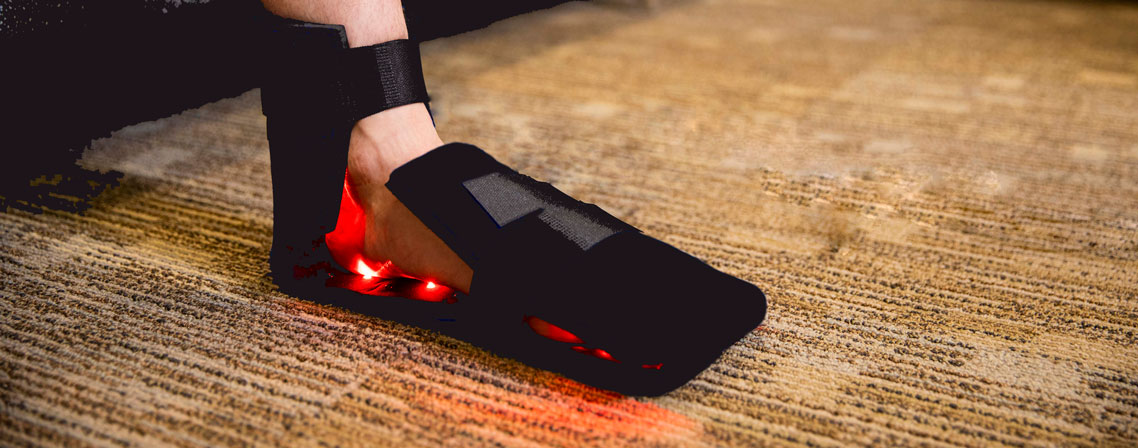
HealthLight is a leading health technology company that specializes in developing and manufacturing innovative therapy pads based on low-level light therapy. Our mission is to provide safe, effective, and affordable solutions to help individuals find relief from pain and improve circulation. HealthLight offers drug-free, non-invasive, medical-grade relief. Our light therapy pads are typically found in doctor~s offices, but are now available to the public.FDA-cleared and backed by 3,000 research studies, HealthLight offers powerful, tested pain relief. Join the thousands of people who got their lives back from often endless pain by using HealthLight light therapy pads at home and wherever they may be. Many of our customers reduce or even eliminate powerful pain meds from their daily regimen. Our team of experts includes doctors, engineers, and scientists who are dedicated to designing and developing cutting-edge technology that delivers real results. Our products are safe and easy to use.At HealthLight, we believe that everyone deserves access to the latest healthcare technology, which is why we offer our products at affordable prices. Our devices are easy to use, portable, and can be used in the comfort of your own home, making them ideal for busy individuals seeking effective pain management and injury recovery.Since our inception, HealthLight has earned a reputation as a trusted provider of health technology solutions. Independent testing has shown that HealthLight therapy pads stand apart from the competition, delivering more light energy to the skin than light therapy pads from other companies. This is due to our exclusive LED technology. If you are looking for a safe, effective, and affordable way to manage pain and improve circulation, look no further than HealthLight.

Learn More

Medical Guardian | Medical Alert Devices

Assistive Devices

As a trusted leader in personal safety and medical alert systems, Medical Guardian has been empowering seniors and their families for over two decades. With a mission to provide safety, security, and peace of mind, Medical Guardian offers state-of-the-art solutions that enable seniors to maintain independence while staying connected to immediate help whenever needed.Who We AreFounded on the belief that everyone deserves to feel safe at home and on the go, Medical Guardian has grown into one of the most recognized names in the personal emergency response industry. With a focus on innovation, accessibility, and reliability, we are committed to delivering products and services that enhance the quality of life for seniors nationwide.Our Solutions: Tailored for Every LifestyleMedical Guardian understands that no two lifestyles are the same, which is why we provide a wide range of medical alert systems to meet unique needs. From home-based devices to on-the-go wearable technology, our solutions are designed to fit seamlessly into daily life. Key offerings include:In-Home Medical Alert SystemsPerfect for seniors who spend most of their time at home, these systems provide 24/7 monitoring through easy-to-use base stations and wearable help buttons. With features like fall detection and two-way communication, help is always just a button press away.Mobile Medical Alert SystemsFor active seniors, our mobile systems offer GPS tracking and nationwide coverage, ensuring safety wherever life takes you. These portable devices are lightweight and discreet, providing peace of mind without compromising mobility.Wearable TechnologyCombining functionality with style, our wearable devices include medical alert watches and pendants equipped with cutting-edge technology. These devices are not only lifesaving tools but also fashionable accessories that integrate seamlessly into any wardrobe.Fall Detection TechnologyFalls are one of the leading causes of injury among seniors. Medical Guardian’s advanced fall detection sensors can automatically alert our monitoring center in case of a fall, even if the user is unable to press the button.Caregiver ToolsMedical Guardian’s products are complemented by innovative caregiver tools, such as activity tracking and location monitoring, to keep loved ones informed and reassured.PERS Solutions for Senior Living CommunitiesMedical Guardian proudly partners with senior living communities to provide Personal Emergency Response Systems (PERS) tailored specifically to the unique needs of Affordable Housing, Independent Living, and Assisted Living environments.Our solutions are designed to increase resident safety, empower staff with reliable tools, and deliver added value to your community. By integrating Medical Guardian’s systems, senior living communities can enhance their reputation as safety-focused environments while offering peace of mind to residents and their families.With flexible plans, seamless integration, and ongoing support, Medical Guardian makes it easy for senior living operators to implement top-tier safety solutions for their residents.Commitment to ExcellenceAt Medical Guardian, safety is more than a product—it’s a promise. Our U.S.-based monitoring centers are staffed by highly trained professionals who are ready to respond within seconds of an alert. With multiple monitoring centers, we ensure redundancy and reliability, so no call goes unanswered.Each product undergoes rigorous testing to meet the highest standards of quality and performance. Additionally, our customer care team is available to guide families and senior living communities through every step, from choosing the right device to troubleshooting and technical support.Why Choose Medical Guardian?National Reach, Local Care: While Medical Guardian serves clients nationwide, our services are personalized to meet the needs of each individual and their community.Proactive Safety Solutions: Our devices go beyond emergency response, offering proactive monitoring and tools that support overall well-being.Affordable Plans: We believe safety should be accessible to everyone, which is why we provide flexible and affordable plans without hidden fees.Trusted by Millions: With thousands of 5-star reviews and endorsements from leading senior-focused organizations, Medical Guardian is a name families and communities can rely on.Empowering IndependenceSeniors face many challenges as they age, but losing independence doesn’t have to be one of them. Medical Guardian’s medical alert systems are designed to empower seniors to live life on their terms, with the freedom to pursue their passions and the confidence that help is always within reach.Whether you’re a senior seeking greater independence, a caregiver looking for peace of mind, or a senior living community exploring safety solutions, Medical Guardian is here to support you every step of the way.For more information, visit MedicalGuardian.com or call 1-800-734-2092 to speak with a representative.

Learn More

Medical Guardian | Medical Alert Systems

Medical Devices

As a trusted leader in personal safety and medical alert systems, Medical Guardian has been empowering seniors and their families for over two decades. With a mission to provide safety, security, and peace of mind, Medical Guardian offers state-of-the-art solutions that enable seniors to maintain independence while staying connected to immediate help whenever needed.Who We AreFounded on the belief that everyone deserves to feel safe at home and on the go, Medical Guardian has grown into one of the most recognized names in the personal emergency response industry. With a focus on innovation, accessibility, and reliability, we are committed to delivering products and services that enhance the quality of life for seniors nationwide.Our Solutions: Tailored for Every LifestyleMedical Guardian understands that no two lifestyles are the same, which is why we provide a wide range of medical alert systems to meet unique needs. From home-based devices to on-the-go wearable technology, our solutions are designed to fit seamlessly into daily life. Key offerings include:In-Home Medical Alert SystemsPerfect for seniors who spend most of their time at home, these systems provide 24/7 monitoring through easy-to-use base stations and wearable help buttons. With features like fall detection and two-way communication, help is always just a button press away.Mobile Medical Alert SystemsFor active seniors, our mobile systems offer GPS tracking and nationwide coverage, ensuring safety wherever life takes you. These portable devices are lightweight and discreet, providing peace of mind without compromising mobility.Wearable TechnologyCombining functionality with style, our wearable devices include medical alert watches and pendants equipped with cutting-edge technology. These devices are not only lifesaving tools but also fashionable accessories that integrate seamlessly into any wardrobe.Fall Detection TechnologyFalls are one of the leading causes of injury among seniors. Medical Guardian’s advanced fall detection sensors can automatically alert our monitoring center in case of a fall, even if the user is unable to press the button.Caregiver ToolsMedical Guardian’s products are complemented by innovative caregiver tools, such as activity tracking and location monitoring, to keep loved ones informed and reassured.PERS Solutions for Senior Living CommunitiesMedical Guardian proudly partners with senior living communities to provide Personal Emergency Response Systems (PERS) tailored specifically to the unique needs of Affordable Housing, Independent Living, and Assisted Living environments.Our solutions are designed to increase resident safety, empower staff with reliable tools, and deliver added value to your community. By integrating Medical Guardian’s systems, senior living communities can enhance their reputation as safety-focused environments while offering peace of mind to residents and their families.With flexible plans, seamless integration, and ongoing support, Medical Guardian makes it easy for senior living operators to implement top-tier safety solutions for their residents.Commitment to ExcellenceAt Medical Guardian, safety is more than a product—it’s a promise. Our U.S.-based monitoring centers are staffed by highly trained professionals who are ready to respond within seconds of an alert. With multiple monitoring centers, we ensure redundancy and reliability, so no call goes unanswered.Each product undergoes rigorous testing to meet the highest standards of quality and performance. Additionally, our customer care team is available to guide families and senior living communities through every step, from choosing the right device to troubleshooting and technical support.Why Choose Medical Guardian?National Reach, Local Care: While Medical Guardian serves clients nationwide, our services are personalized to meet the needs of each individual and their community.Proactive Safety Solutions: Our devices go beyond emergency response, offering proactive monitoring and tools that support overall well-being.Affordable Plans: We believe safety should be accessible to everyone, which is why we provide flexible and affordable plans without hidden fees.Trusted by Millions: With thousands of 5-star reviews and endorsements from leading senior-focused organizations, Medical Guardian is a name families and communities can rely on.Empowering IndependenceSeniors face many challenges as they age, but losing independence doesn’t have to be one of them. Medical Guardian’s medical alert systems are designed to empower seniors to live life on their terms, with the freedom to pursue their passions and the confidence that help is always within reach.Whether you’re a senior seeking greater independence, a caregiver looking for peace of mind, or a senior living community exploring safety solutions, Medical Guardian is here to support you every step of the way.For more information, visit MedicalGuardian.com or call 1-800-734-2092 to speak with a representative.

Learn More

HealthLight Light Therapy Devices

Pain Management

HealthLight is a leading health technology company that specializes in developing and manufacturing innovative therapy pads based on low-level light therapy. Our mission is to provide safe, effective, and affordable solutions to help individuals find relief from pain and improve circulation. HealthLight offers drug-free, non-invasive, medical-grade relief. Our light therapy pads are typically found in doctor~s offices, but are now available to the public.FDA-cleared and backed by 3,000 research studies, HealthLight offers powerful, tested pain relief. Join the thousands of people who got their lives back from often endless pain by using HealthLight light therapy pads at home and wherever they may be. Many of our customers reduce or even eliminate powerful pain meds from their daily regimen. Our team of experts includes doctors, engineers, and scientists who are dedicated to designing and developing cutting-edge technology that delivers real results. Our products are safe and easy to use.At HealthLight, we believe that everyone deserves access to the latest healthcare technology, which is why we offer our products at affordable prices. Our devices are easy to use, portable, and can be used in the comfort of your own home, making them ideal for busy individuals seeking effective pain management and injury recovery.Since our inception, HealthLight has earned a reputation as a trusted provider of health technology solutions. Independent testing has shown that HealthLight therapy pads stand apart from the competition, delivering more light energy to the skin than light therapy pads from other companies. This is due to our exclusive LED technology. If you are looking for a safe, effective, and affordable way to manage pain and improve circulation, look no further than HealthLight.

Learn More

Educate Yourself-Read the Latest Articles

What Does a Client Care Advocate Do? A Guide for Navigating Elder Care

Caring for an aging parent or loved one often raises difficult questions. How do you know when they need additional support? What happens if their health changes? And where can you turn when youre unsure which care options are best?A client care advocate helps you navigate these decisions by identifying resources, coordinating care, and providing guidance as your loved ones needs change. Whether they want to remain at home or require additional assistance, professional support can help you make informed choices that protect their independence and quality of life.What Is a Client Care Advocate?A client care advocate is a professional who helps older adults and their families navigate healthcare services, long-term care options, and the challenges of aging. They help you understand your loved ones needs, explore available resources, and make informed care decisions.While healthcare providers address medical needs, a client care advocate focuses on practical concerns such as living arrangements, daily activities, personal preferences, and family support. For example, your mother may be able to live independently but struggle with transportation or household responsibilities. An advocate can help you explore services that address these challenges without immediately considering assisted living.When a client care advocate works alongside an elder law attorney, your family can address practical care needs and legal considerations through a coordinated approach. This can be especially helpful when changing care needs affect important financial or long-term planning decisions.What Does a Client Care Advocate Do for Your Family?A client care advocate provides guidance based on your loved ones circumstances. Their primary responsibilities include assessing needs, connecting families with services, and assisting during care transitions.Assess Your Loved Ones Care NeedsUnderstanding your loved ones situation is the foundation of effective care planning. An advocate considers their living arrangements, daily activities, support system, personal preferences, and potential safety concerns.If your father recently experienced a fall, for example, an advocate can help you identify concerns, explore available assistance, and prepare questions for healthcare professionals. This gives you a clearer understanding of the factors that may affect his ability to continue living independently.Coordinate Elder Care Services and ResourcesFinding appropriate elder care services can be challenging when youre unfamiliar with local programs and providers. Your advocate can help you identify resources based on your loved ones circumstances and the level of assistance they need.Depending on those needs, an advocate may help you explore: In-home care and personal assistance Meal delivery and transportation Adult day programs Assisted living and skilled nursing facilities Caregiver support and respite services Having guidance about available services can make it easier to compare options and determine which arrangements may be appropriate. Its particularly helpful when your loved one requires assistance from multiple providers.Support Healthcare and Living TransitionsA hospitalization, new diagnosis, or decline in mobility may require changes to your loved ones care arrangements. Your advocate can help you understand available options, communicate with providers, and prepare for transitions between care settings.For example, if your father is leaving a rehabilitation facility, you may need to determine whether he can safely return home. An advocate can help you evaluate his assistance needs and identify services that could support his recovery.How a Client Care Advocate Supports Aging in PlaceMany older adults prefer remaining at home rather than moving into assisted living or another care facility. However, aging in place requires balancing independence with safety and appropriate support. A client care advocate helps you evaluate whether your loved ones home environment can continue meeting their needs.Recognize Potential Safety ConcernsChanges in health or mobility can make everyday activities more challenging. Stairs, bathrooms, and household tasks may create safety concerns that werent previously present.Your advocate can help identify potential risks and explore resources such as home safety assessments, accessibility improvements, or additional in-home assistance. These adjustments may help your loved one maintain independence while addressing concerns about their living environment.Prepare for Changing Care NeedsA care arrangement that works today may need adjustments as your loved one ages. Someone who currently lives independently might eventually require assistance with personal care or supervision.For example, a parent living with dementia may initially need occasional help but require more consistent support as their condition progresses. An advocate can help you recognize when existing arrangements may no longer be sufficient and explore alternatives that reflect your loved ones changing needs.How Client Care Advocates Help Family CaregiversSupporting an aging loved one can be demanding when youre balancing employment, household responsibilities, and other commitments. You may spend considerable time coordinating appointments, researching services, and communicating with providers. A client care advocate offers guidance that can make these responsibilities more manageable.Simplify Care DecisionsWhen several concerns arise at once, knowing what to address first can be difficult. You might be worried about your parents safety while also trying to arrange transportation or additional assistance.Your advocate can help clarify priorities and identify practical next steps, allowing you to approach decisions with greater confidence. Instead of navigating unfamiliar care options alone, you have a knowledgeable professional who can help you understand the choices available.Navigate Family DisagreementsFamily members dont always agree about an aging parents care. One sibling may believe assisted living is necessary, while another prefers additional home support.A client care advocate can help your family evaluate available options while keeping your loved ones preferences and care needs central to the discussion. Having a professional perspective can make difficult conversations more productive, even when family members have different opinions.Client Care Advocate vs. Elder Law Attorney: Whats the Difference?A client care advocate and an elder law attorney serve different but complementary roles. Understanding the distinction can help you recognize how each professional supports your familys planning needs.An elder law attorney addresses legal matters affecting older adults, including estate planning, powers of attorney, Medicaid planning, asset protection, and long-term care considerations. A client care advocate focuses on practical care needs, resource coordination, and guidance through changing health or living circumstances.For example, if your mother needs skilled nursing care, an elder law attorney can explain relevant legal and financial planning options. Meanwhile, a client care advocate can help you explore care arrangements and communicate with providers.Working with both professionals allows you to consider immediate care concerns alongside long-term legal planning. This approach can help you make decisions that reflect your loved ones needs and your familys broader circumstances.The Role of a Client Care Advocate in Life Care PlanningLife care planning brings together legal guidance and care coordination to help families prepare for challenges associated with aging, long-term illness, or incapacity. While traditional estate planning generally focuses on legal documents and the distribution of assets, life care planning also considers your loved ones needs during their lifetime.Bellomo & Associates offers life care planning services that combine the experience of our elder law attorneys with the guidance of our client care advocates. This approach helps you address practical care decisions while considering legal and financial planning needs.Support as Circumstances ChangeYour loved ones care requirements may change following a diagnosis, hospitalization, or move to a different living environment. These developments can also affect your familys legal and financial planning needs.Through life care planning, our team helps you evaluate changing circumstances and consider appropriate next steps. By bringing care advocacy and elder law guidance together, we help you make decisions that reflect both current needs and long-term goals.When Should You Contact a Client Care Advocate?You dont need to wait for a medical emergency to seek guidance. Recognizing changes early gives your family more time to discuss preferences and consider appropriate care arrangements.Common signs that you may benefit from a client care advocate include: Difficulty with daily activities: Your loved one struggles with bathing, cooking, or household tasks. A new diagnosis: Youre uncertain how an illness may affect future care needs. Recent falls or hospitalizations: Youre concerned about safety or recovery at home. Increasing caregiver demands: Youre struggling to manage caregiving responsibilities. Long-term care questions: Youre considering assisted living or skilled nursing care. Family disagreements: You need guidance evaluating different care options. Even if your loved one is currently independent, discussing future needs can help your family prepare before circumstances become urgent. An early conversation may also help you understand which resources could become useful as their needs change.How to Prepare for Your First Meeting With a Client Care AdvocateYour first meeting is an opportunity to discuss concerns, understand available resources, and identify your loved ones care priorities. You dont need every answer beforehand, but gathering basic information can help make the conversation productive.Gather Relevant InformationReview your loved ones living arrangements, health concerns, daily routines, and current support services. Consider which activities have become more difficult and whether recent changes have raised safety concerns.You should also identify family members involved in caregiving and any immediate issues requiring attention. Having this information available helps your advocate better understand your loved ones situation and the support your family may need.Prepare Your QuestionsBefore your meeting, consider what youd most like to understand about your loved ones care. Think about their current needs, potential changes, and any decisions your family may be struggling to make.Helpful questions include: Which care options fit their current needs? What resources could help them remain at home? How can we prepare for changing health conditions? When should we consider a higher level of care? How will care coordination work as needs change? These questions can help you establish priorities and understand what to expect from the planning process. They also give you an opportunity to discuss your concerns before making significant care decisions.Find Client Care Advocate Services in York and Lancaster, PAWorking with professionals familiar with your community can help you locate appropriate services and navigate local care options. Having access to knowledgeable guidance is especially valuable when your loved ones needs change or youre considering unfamiliar care arrangements.Bellomo & Associates serves families throughout York, Lancaster, and surrounding Pennsylvania communities. Our elder law and life care planning services help families address legal considerations alongside the practical challenges of aging.Our client care advocates help you understand available care arrangements, identify resources, and respond to changing needs. Whether your loved one lives independently or requires additional assistance, were here to help you evaluate your options and make informed decisions.Get Trusted Elder Care Guidance From Bellomo & AssociatesUnderstanding what a client care advocate does can help you make informed decisions about your loved ones care. With professional guidance, you can explore appropriate services, navigate transitions, and prepare for changing needs without managing every responsibility alone.Bellomo & Associates combines elder law guidance with personalized care advocacy through our life care planning services. Were here to help you address todays concerns while planning for the future. Contact Bellomo & Associates to learn how our client care advocates can support you and your family.  

Traditional IRA vs Roth IRA: When Not to Convert

Roth conversions have become an increasingly common topic in retirement planning conversations. The idea of paying taxes today in exchange for potentially tax-free withdrawals later can sound appealing.But heres an important question: What if keeping your traditional IRA is actually the better financial decision?While Roth IRAs offer meaningful tax advantages, converting retirement savings isnt automatically appropriate for everyone.In fact, depending on your current tax bracket, future income, charitable giving plans, and estate planning goals, maintaining some or all of your savings in a traditional IRA may make more sense.At Nova Wealth Management, we believe the traditional IRA vs Roth IRA decision should be evaluated within your overall retirement income strategy rather than based on general assumptions about future tax rates.TRADITIONAL IRA VS ROTH IRA: UNDERSTANDING THE DIFFERENCEBoth traditional and Roth IRAs provide tax advantages, but those advantages generally occur at different times.Traditional IRA: Contributions may be tax-deductible depending on eligibility and income. Investments generally grow tax-deferred, and withdrawals are typically subject to ordinary income tax, except for amounts attributable to previously taxed contributions.Roth IRA: Contributions are made with after-tax dollars. Investments may grow tax-free, and qualified withdrawals are generally tax-free.A Roth conversion involves transferring funds from a traditional retirement account into a Roth account. The taxable portion of the converted amount is generally included in income for the year of conversion.That creates an important trade-off: Pay taxes now or potentially pay them later.The appropriate choice depends on more than whether tax-free withdrawals sound attractive.1. YOUR CURRENT TAX BRACKET MAY MAKE A ROTH CONVERSION EXPENSIVEOne of the first considerations is the tax cost of converting.Imagine youre still working and earning a substantial income. Converting a large traditional IRA balance could increase your taxable income and potentially move some of that income into a higher marginal tax bracket.The additional income could also affect other tax-related calculations.Depending on your circumstances, a Roth conversion may influence:The taxation of Social Security benefitsMedicare Part B and Part D income-related premiums (IRMAA)Eligibility for certain deductions or tax benefitsThe net investment income tax calculationIf you anticipate being in a lower tax bracket during retirement, paying taxes on a conversion today may not be advantageous.However, future tax rates and personal circumstances are uncertain, which is why individual tax projections matter.2. CHARITABLE GIVING MAY FAVOR KEEPING A TRADITIONAL IRAFor retirees who regularly support charitable organizations, traditional IRAs can provide an important planning opportunity.Individuals age 70 or older may be eligible to make qualified charitable distributions (QCDs) directly from an IRA to qualifying charities.When applicable requirements are satisfied, these distributions can be excluded from taxable income and may count toward required minimum distributions.For someone planning significant charitable gifts, maintaining traditional IRA assets may preserve opportunities that would otherwise be reduced by converting those funds to a Roth IRA.QCDs are subject to eligibility requirements, annual limits, and other rules.A Roth conversion shouldnt be evaluated without considering how charitable giving fits into your retirement and estate planning goals.3. PAYING CONVERSION TAXES REQUIRES CAREFUL PLANNINGA Roth conversion creates a tax obligation even though the converted money remains invested in a retirement account.Many individuals prefer to pay conversion taxes using funds outside their retirement accounts.Using outside funds may preserve more money inside the Roth IRA for potential future tax-free growth.However, paying the taxes from other assets can reduce available liquidity and may create additional tax consequences if investments must be sold.If you dont have sufficient accessible assets to cover the conversion taxes, the financial trade-offs deserve particularly careful consideration.And unlike in the past, a completed Roth conversion generally cannot be reversed through recharacterization.That makes evaluating the potential tax consequences before converting especially important.4. YOUR BENEFICIARIES TAX BRACKETS COULD CHANGE THE EQUATIONRoth conversions can also affect what beneficiaries eventually receive.Inherited traditional IRA distributions are generally taxable to beneficiaries, except for any applicable after-tax basis. Qualified distributions from inherited Roth IRAs are generally tax-free.However, that doesnt automatically mean converting is better for your heirs.Consider a retiree who is currently in a relatively high tax bracket but expects to leave retirement assets to adult children in lower tax brackets.Paying conversion taxes at the parents higher rate may create a different family-wide tax outcome than leaving traditional IRA assets for beneficiaries to withdraw later.Many non-spouse beneficiaries must empty inherited IRAs within 10 years, although annual distribution requirements and exceptions depend on individual circumstances.Estate planning should consider both the value of inherited assets and how those assets may be taxed.5. THE YEARS BETWEEN RETIREMENT AND RMDS MAY OFFER OPPORTUNITIESFor some retirees, the period after leaving the workforce but before required minimum distributions begin may provide opportunities to evaluate Roth conversions.During these years, employment income may have stopped while Social Security benefits or RMDs have not yet begun.That could create comparatively lower-income years.However, RMD starting ages vary based on birth year, and Roth conversions can affect other financial considerations even during lower-income periods.Rather than converting an entire account at once, some individuals may benefit from evaluating partial conversions over multiple years.The appropriate approach depends on projected taxes, income needs, Medicare considerations, and the broader retirement plan.6. HEALTH SAVINGS ACCOUNTS MAY DESERVE ATTENTION TOOFor eligible individuals, a Health Savings Account (HSA) may provide another tax-advantaged savings opportunity.HSAs can offer tax-deductible or pretax contributions, tax-deferred growth, and tax-free withdrawals for qualified medical expenses.However, eligibility requirements apply, and individuals enrolled in Medicare generally cannot make additional HSA contributions.HSAs serve a different purpose than IRAs, so the appropriate contribution strategy depends on healthcare needs, eligibility, and overall financial circumstances.FREQUENTLY ASKED QUESTIONS ABOUT TRADITIONAL AND ROTH IRASIS A ROTH IRA ALWAYS BETTER THAN A TRADITIONAL IRA?No. Roth IRAs offer potential tax-free qualified withdrawals, but traditional IRAs may be advantageous when current tax rates are higher than expected future rates or when certain charitable giving strategies are important.CAN A ROTH CONVERSION INCREASE MEDICARE PREMIUMS?Yes. Taxable Roth conversions may increase modified adjusted gross income used to calculate Medicare IRMAA. Medicare generally uses income information from two years earlier when determining these additional premiums.SHOULD I CONVERT MY ENTIRE TRADITIONAL IRA TO A ROTH IRA?Not necessarily. A full conversion can create substantial taxable income. Partial conversions may be worth evaluating, but the appropriate strategy depends on your individual tax situation and retirement objectives.INVESTMENT TYPES AND ACCOUNTS TO CONSIDERWhen evaluating traditional and Roth IRA strategies, several accounts may be relevant:Traditional IRA: Tax-deferred retirement savings with generally taxable withdrawals.Roth IRA: After-tax retirement savings with potentially tax-free qualified withdrawals.Traditional and Roth 401(k): Employer-sponsored retirement accounts with different tax treatments.Health Savings Account (HSA): Tax-advantaged savings for eligible healthcare expenses.Brokerage Account: Taxable investments that may provide liquidity for retirement expenses or conversion taxes.NEXT STEPS: SHOULD YOU KEEP YOUR TRADITIONAL IRA OR CONSIDER A ROTH CONVERSION?The decision isnt simply about whether Roth IRAs or traditional IRAs are better.Its about understanding which approach may be appropriate for your retirement income, tax situation, charitable goals, and estate plan.At Nova Wealth Management, we help individuals and families in Bonita Springs, Naples, Estero, Fort Myers, Dallas, and throughout the country evaluate retirement income strategies and tax-aware financial planning.Before making a Roth conversion, consider reviewing how the decision could affect your broader financial plan.Schedule your planning session with Nova Wealth Management.Contact Nova Wealth Management:Toll-Free: 1-888-677-9910Bonita Springs: 239-444-1794Dallas: 214-272-2336Source: Forbes, Bob Carlson, October 29, 2026. Licensed through AdvisorStream.Disclosure: This material is provided for general educational and informational purposes only and does not constitute individualized investment, tax, or legal advice. Roth conversions are generally taxable and cannot be reversed through recharacterization. Retirement account rules and tax laws may change. Consult qualified tax and financial professionals before making retirement account decisions. Investing involves risk, including possible loss of principal. Nova Wealth Management, Inc. is a Registered Investment Advisor.

Adding a Child to Your House Deed?

A parent may spend considerable time deciding how a home should be divided among children in a will or trust, then make one seemingly simple change that alters the entire plan: adding one child to the deed. The reason is easy to miss. A will and a deed do different jobs. Your will controls certain property that remains part of your probate estate when you die. A deed establishes ownership of real estate during your lifetime and can determine what happens to an ownership interest at death, depending on how the property is titled. Entrusted Legacy Law's overview of estate planning in Pennsylvania explains why an effective plan needs to address both legal documents and the way assets are actually owned.This distinction matters when a parent adds one child to a house deed because the goal is often innocent: make the transfer easier, avoid probate, reduce taxes, or give a responsible child authority to help with the property. The result, however, may be very different from what the parent intended. Before changing a deed, Pennsylvania homeowners need to understand what they are giving away, how the new ownership fits with their will or trust, and what tax, long-term care, and family consequences may follow. Your Will Doesn't Necessarily Control Everything You Own One of the most important estate planning concepts is the difference between probate and non-probate property. A will generally directs the distribution of property that becomes part of your probate estate. Other assets may transfer according to their title, beneficiary designation, trust ownership, or another legal arrangement instead. Entrusted Legacy Law's explanation of the Pennsylvania probate process notes that individually owned property may be subject to probate, while properly structured jointly owned property can transfer through title rather than through the will. That means the sentence in your will that says, for example, "I leave my estate equally to my three children" does not necessarily mean every asset you own will ultimately be divided three ways. Imagine a mother named Linda has three adult children: Claire, Michael, and Sarah. Her will says her estate should be divided equally among them. Linda later adds Claire to the deed to her house because Claire lives nearby and helps manage repairs and household matters. Linda assumes the house will still be divided among all three children because that is what her will says. That assumption may be wrong. What happens depends on exactly how the deed is written. Certain forms of joint ownership can include survivorship rights, meaning the surviving owner receives the deceased owner's interest through the title arrangement. Other forms of co-ownership do not work that way. The important point is not that every joint deed produces the same result. It is that the deed itself matters, and changing ownership without reviewing the estate plan can produce a transfer that differs from the parent's expectations. Adding a Child to a Deed Is an Ownership Decision Families sometimes describe this transaction casually: "I am just putting her name on the house." Legally, the word "just" can hide a significant change. A properly completed transfer can give the child a present ownership interest in the real estate. The property is no longer owned solely by the parent. Exactly what rights each person receives depends on the language of the deed and the form of ownership created. That distinction matters because an estate plan should answer two separate questions: Who owns the property now? Who should own it after the current owner dies? A will primarily addresses the second question for probate property. A deed can change the answer to the first question immediately. For a family whose primary goal is simply to make administration easier after death, transferring ownership during life may be a much larger legal step than necessary. One Child on the Deed Can Affect the Intended Division Among Siblings A common concern arises when a parent intends to treat several children equally but adds only one child to the deed. Often, the child being added is not intended to receive a larger inheritance. That child may simply live nearby, help with the home, or be viewed as the family member who will handle practical matters later. The parent may assume that child will "do the right thing" and divide the property with siblings. That is not the same as having an estate plan that legally produces the intended result. Family relationships can also change. A child may die before the parent. Siblings may disagree about whether the deed was intended as a gift. Financial circumstances may change. The child on the deed may develop different expectations about the property after contributing toward repairs, taxes, or maintenance. Good estate planning does not depend on everyone remembering an informal conversation the same way years later. The ownership documents, will, trust, and overall distribution plan should tell the same story. The Child's Financial Life Can Become Relevant to the Property Transferring an ownership interest also means the parent's house is no longer connected only to the parent's legal and financial circumstances. The child's interest is now an asset belonging to the child. Depending on the circumstances, legal claims involving that child may affect that interest. That can include creditor problems or litigation. Divorce can also require additional analysis. Pennsylvania law generally excludes property acquired by gift from the definition of marital property, but the law specifically addresses increases in the value of certain nonmarital property, and the outcome of a divorce depends on the facts and how the property has been treated. The Pennsylvania statute governing marital property illustrates why a simple statement that a gifted property interest is either completely "safe" or automatically divided in divorce would be too broad. This is one reason families benefit from discussing the child's circumstances before making the transfer. An ownership change designed to simplify one problem can introduce another set of variables that did not exist while the parent owned the home alone. Adding a Child to the Deed Does Not Automatically Eliminate Pennsylvania Inheritance Tax Taxes are another frequent motivation for deed changes. Pennsylvania imposes an inheritance tax on many transfers occurring at death. The rate generally depends on the relationship between the person who died and the recipient. The Pennsylvania Department of Revenue's inheritance tax guidance currently lists a 4.5 percent rate for transfers to direct descendants and lineal heirs. Transfers to a surviving spouse are generally taxed at zero percent. Adding a child to a deed should not be treated as a simple method for making Pennsylvania inheritance tax disappear. The timing of a transfer, the ownership structure, how the property passes at death, and other facts can affect the analysis. Families who are concerned primarily about inheritance tax can learn more through Entrusted Legacy Law's guide to Pennsylvania inheritance tax planning. A revocable living trust, for example, may help property avoid probate when properly funded, but it does not by itself eliminate Pennsylvania inheritance tax. The tax question therefore needs to be considered as one part of the estate plan rather than as the sole reason for changing ownership of the home. Lifetime Transfers Can Also Change Federal Income Tax Considerations Pennsylvania inheritance tax is not the only tax issue worth reviewing. When property is given during the owner's lifetime, federal tax basis rules can differ from the rules that generally apply to property acquired from someone who has died. The Internal Revenue Service guidance on the basis of gifted property explains that determining a recipient's basis in gifted property can require consideration of the donor's adjusted basis, the property's fair market value at the time of the gift, and, when applicable, gift tax paid. That matters because basis is used when calculating gain or loss if property is later sold. For a home that has appreciated substantially over decades, transferring an interest during life without considering basis could create a different tax outcome from allowing property to pass at death. This does not mean every lifetime transfer produces a large tax bill. It means tax consequences should be calculated rather than assumed. An estate planning attorney may also coordinate with the family's certified public accountant or other tax professional when the numbers warrant additional tax analysis. A Deed Transfer Can Matter for Future Medicaid Planning For older homeowners, long-term care planning adds another important consideration. Pennsylvania's Department of Human Services reviews certain asset transfers made during the 60 months before an applicant seeks Medicaid coverage for long-term care. According to the state's Medical Assistance guidance for long-term care, assets transferred, sold, or given away during that look-back period must be reviewed. When fair market value was not received, a period of ineligibility may result, subject to applicable rules and exceptions. A parent who gives a child an ownership interest in a home may therefore be making more than an estate planning decision. The transfer may also become relevant if long-term care is needed later. There are important exceptions and planning strategies under Medicaid rules, so families should not assume that every deed transfer is prohibited or that every home must remain untouched. The appropriate strategy depends on factors such as health, marital status, other assets, timing, and long-term goals. Entrusted Legacy Law's elder law and Medicaid planning services focus on evaluating those issues together rather than treating the house, Medicaid eligibility, and the estate plan as separate problems. The Deed Can Affect Your Ability to Change Course Later Another question homeowners sometimes overlook is what happens if they change their minds. A parent who remains the sole owner generally has significant control over decisions involving the property. Once another person receives an ownership interest, changing that arrangement can require the cooperation of the other owner and additional legal documentation. That matters because life rarely stays exactly as it was when an estate plan was first created. A parent may later want to sell the house and downsize. -The child may move away. -The parent may remarry. -One sibling may become the primary caregiver. -The home may need to be sold to help fund care. -Family relationships may change. A planning decision that seemed appropriate at age 65 may be inconvenient at 78. Preserving appropriate flexibility is therefore an important part of evaluating any lifetime transfer. Avoiding Probate Is a Goal, Not a Complete Estate Plan Some parents add a child to a deed for one reason: they do not want their home to go through probate. That is a legitimate planning goal, but the method matters. Entrusted Legacy Law's probate guidance explains that property can sometimes pass outside probate through title, and assets properly owned by a trust may also avoid probate.   The question is not simply whether a strategy avoids probate. The better question is what else the strategy changes. An option that avoids probate but creates an unintended gift, changes the inheritance among children, complicates long-term care planning, or produces unfavorable tax consequences may not accomplish the family's larger objectives. Estate planning works best when probate avoidance is considered alongside control, taxes, creditor concerns, long-term care, family relationships, and the eventual distribution of property. What Should You Review Before Adding a Child to Your Deed? Before signing a new deed, it helps to be clear about the problem you are trying to solve. Ask yourself: Am I trying to avoid probate? Am I trying to reduce inheritance tax? Do I want my child to own part of the property now? Do I simply want someone to help manage financial matters? Do I intend this child to receive the entire home after my death? Should the home's value be divided among several beneficiaries? Could I need long-term care in the next several years? How would this transfer fit with my existing will or trust? What happens if my child dies before me? What happens if I later want to sell or change the plan? The answers may point toward very different planning tools. Someone who needs assistance managing finances may need a properly drafted financial power of attorney rather than a new co-owner. Someone whose primary concern is probate may need to review trust planning and asset titling. Someone focused on nursing home costs may need elder law and Medicaid planning. Someone who wants several children to benefit from the property may need a structure that clearly defines how and when each person's interest is received. There is no universal deed arrangement that solves every estate planning problem. Why Coordinating the Deed, Will, and Trust Matters An estate plan is not merely a collection of signed documents. A beautifully drafted will cannot accomplish its intended purpose if major assets pass according to ownership arrangements that were never reviewed. A trust cannot govern real estate that was meant to be placed into the trust but was never properly transferred. A tax strategy can fail if it addresses one tax while ignoring another consequence. The more useful approach is to review the family, the documents, and the assets together. For a homeowner, that means looking at the actual deed rather than relying on memory about how the property is titled. It also means comparing the deed with the will or trust and asking whether each document produces the same intended result. For parents with several children, the question becomes especially important. If one child appears on the deed and all children appear in the will, there should be a clear reason for that difference. Before You Sign a New Deed, Understand What It Changes Adding a child to a deed is not automatically wrong. There are situations in which a carefully planned property transfer can serve a legitimate purpose. The risk comes from treating the deed as harmless paperwork. Changing a deed can affect present ownership, the way property passes at death, the relationship between the home and the will, potential tax treatment, future Medicaid planning, and the legal interests of other family members. The right answer depends on what the family is actually trying to accomplish. If you are considering adding a child to your Pennsylvania property, or you already made a deed change and want to know whether it still matches your estate plan, Entrusted Legacy Law can help you review the entire picture. Schedule an introductory consultation to discuss your goals before making another change. This article is for educational purposes and is not legal or tax advice. The effect of a deed depends on its language and the facts of the individual situation. In Pennsylvania, a will does not necessarily control what happens to a house. The result depends on how the property is titled. Adding a child to a deed can create a present ownership interest and may affect inheritance, taxes, Medicaid planning, and family rights, so the deed should be reviewed with the complete estate plan. Frequently Asked Questions Does a will override a deed in Pennsylvania? Generally, a will does not simply override an existing property ownership arrangement. A will governs property that passes through the probate estate, while certain ownership arrangements can determine how property transfers outside probate. The language of the deed needs to be reviewed to determine what happens to the property. If I add one child to my deed, do my other children still inherit part of the house? Not necessarily. The result depends on the type of ownership created by the deed and your overall estate plan. A provision dividing your estate among several children may not control an interest that transfers through a different ownership arrangement. Can adding my child to my deed avoid probate in Pennsylvania? Certain forms of joint ownership can cause a property interest to pass outside probate, but avoiding probate does not by itself mean the strategy is appropriate. The transfer can also affect control, taxes, long-term care planning, and the intended inheritance of other family members. Does adding a child to a deed avoid Pennsylvania inheritance tax? It should not be assumed that adding a child eliminates inheritance tax. Pennsylvania's inheritance-tax rules depend on the relationship between the deceased person and the recipient and on how property is transferred. Direct descendants are generally subject to a 4.5 percent rate on taxable transfers. Can adding a child to my house affect Medicaid eligibility? It can. Pennsylvania reviews certain asset transfers made during the 60 months before an application for Medicaid long-term care. A transfer for less than fair market value can create an eligibility penalty, although exceptions and specialized planning rules may apply. Can my child's divorce affect a house I added them to? Potentially, but the answer is fact-specific. Pennsylvania generally excludes property acquired by gift from marital property, while increases in value of certain nonmarital property can be treated differently. Ownership, contributions, timing, and other circumstances should be reviewed before assuming the property is unaffected by a divorce. Is a trust better than adding my child to the deed? It depends on the goal. A properly designed and funded trust can be useful when a family wants to coordinate property management and transfer while maintaining a structured estate plan. Medicaid planning, tax planning, probate avoidance, and family circumstances can require different types of trusts or other strategies.

Adding a Child to Your Bank Account

Adding an adult child to your checking or savings account can seem like an easy way to get help with bills, keep an eye on transactions, or make sure someone can step in if you are unable to manage things yourself. The problem is that adding someone as a joint owner can do more than give them access to the account. It can also affect who owns the money and what happens to it after you die.That distinction matters, especially if you have more than one child and intend for your estate to be divided equally.Joint Owner Is More Than Someone Who Helps With BillsMany parents add a son or daughter to an account for convenience. The child may live nearby, help with monthly expenses, or monitor the account for unusual activity. The parent may think of the arrangement as simple permission to help.Legally, joint ownership can mean something more.Under Pennsylvania law governing multiple-party accounts, the balance remaining in a joint account generally belongs to the surviving party after one owner dies, unless there is sufficient evidence showing a different intent.That means an account you intended to make easier to manage could end up passing differently than the rest of your estate.What If You Have Three Children?Imagine you have three adult children and want everything divided equally among them.One child lives nearby and helps you pay bills, so you add that child to your checking account. Your will still says your estate should be divided equally among all three children.You may assume the money in the checking account will also be divided three ways. If the account is owned jointly with survivorship rights, the remaining balance may pass directly to the surviving joint owner instead of becoming part of the estate distributed under your will.The child on the account may end up receiving more than the others, even though that was never your intention. This does not necessarily mean anyone did anything wrong. It means the account ownership and the estate plan were not working together.Your Will Does Not Control Every AssetA will is an important part of an estate plan, but it does not automatically control everything you own.Some assets pass outside probate because of the way they are titled or because a beneficiary has already been named.Joint accounts are one example. Retirement accounts and life insurance policies can also pass according to beneficiary designations rather than the instructions in a will.This is why good estate planning involves looking at the full picture. Your accounts, beneficiary designations, will, trust, and other planning documents need to support the same goals.Entrusted Legacy Law explains more about this distinction on its Pennsylvania probate page and in its guidance on beneficiary designations and probate.You May Need Authority, Not OwnershipThere is an important question to ask before adding a child to an account:Do you actually want your child to own the account, or do you simply want them to be able to help you?Those are two different goals.If your main concern is giving someone the ability to pay bills or manage finances for you, a financial power of attorney may be worth considering.The Consumer Financial Protection Bureau explains that a power of attorney can allow a trusted person to assist with banking without necessarily making that person a joint owner of the account.A financial power of attorney allows you to name someone to act on your behalf within the authority provided in the document.That can be especially helpful if you become sick, have difficulty managing finances, or simply want someone you trust to assist you.Entrusted Legacy Law also explains the role of this document in Why a Financial Power of Attorney Is More Important Than a Will. Trusting Your Child Does Not Eliminate the ProblemParents sometimes respond to this concern by saying, I trust my daughter. She knows she is supposed to divide the money with her brothers.That trust may be completely justified. The issue is that the family is now depending on an informal conversation instead of a legal plan.Years later, questions can arise.Was the daughter supposed to divide everything equally? Was she supposed to receive something extra because she provided care? Were bills supposed to be paid first? Did the parent change their mind at some point?Even close families can remember conversations differently. Clear planning removes as much uncertainty as possible so your children are not left trying to interpret your wishes after you are gone.What If You Added a Child to Monitor for Fraud?Some parents add a child to an account because they want another set of eyes watching for unusual transactions.That can be a reasonable concern, especially as people get older. Joint ownership, however, may not be the only option.Some financial institutions offer account alerts, limited-access arrangements, trusted contacts, or other ways to involve another person. Options vary from one institution to another.Before changing ownership of an account, ask the bank what alternatives are available and consider how each option fits into your estate plan. Review Accounts You Already Own JointlyThis issue is not limited to people thinking about opening a new account.If you already have an adult child listed on a checking or savings account, it is worth reviewing the arrangement.Ask yourself why that person was originally added and whether the account still reflects what you want today.You should also make sure you understand what happens to the account when you die and whether that result matches your will or trust.An arrangement that made sense ten years ago may no longer fit your family or your estate plan.Make Sure Your Accounts Match Your Estate PlanAdding an adult child to a bank account is not automatically a bad decision. In some families, joint ownership may be intentional and appropriate.The key is understanding what you are creating.If you want your child to own the money with you and potentially receive the account after your death, joint ownership may fit your goals.If you only want someone to help manage bills or finances, another option may make more sense.Entrusted Legacy Law helps Pennsylvania families review how bank accounts, wills, trusts, powers of attorney, and beneficiary designations work together. If you are unsure whether your accounts match the plan you have in mind, you can schedule an introductory consultation.This article is for general educational purposes and is not legal advice. The right approach depends on your account documents, family circumstances, and overall estate plan.
Assisted Living by City